Best Budgeting Apps in Singapore for 2026
Singapore is one of the easier places in the world to budget with automatic data. SGFinDex, a government-backed framework, lets apps consolidate your bank, CPF, HDB loan and investment information with your consent — and the local favourite, Seedly, is built around exactly this. For most Singaporeans, that integrated picture is the sensible default. This guide covers the apps that do it best, and is honest about where Hunter Vault fits: not as a Seedly replacement for everyone, but for the narrower group who would rather not link everything through SGFinDex, or who keep abandoning budgeting apps and want something that actually holds their attention.
On this page
Our picks for different budgeters
Side-by-side comparison
| App | Best for | Price | Bank sync | Manual entry | Debt tracking | Savings goals | Platforms |
|---|---|---|---|---|---|---|---|
| Seedly | Integrated local finances (SGFinDex, CPF) | Free | Yes — via SGFinDex + bank imports | Yes | Limited | Yes | iOS, Android |
| DBS NAV Planner | DBS/POSB customers | Free (within DBS app) | Yes — DBS + SGFinDex | Limited | Limited | Yes | iOS, Android |
| Hunter Vault Our app | Private, gamified manual budgeting | Free / one-time Elite (check SG price) | No — manual, nothing linked | Yes | Yes | Yes | iOS, Android |
| Planner Bee | Spending + insurance + investments | Free (check listing) | Partial / manual | Yes | Limited | Yes | iOS, Android |
| YNAB | Zero-based budgeting method | USD $14.99/mo or $109/yr | No local SG sync | Yes | Yes | Yes | iOS, Android, Web |
| Monefy | Fast simple expense logging | Free (ads) / ~Pro (check listing) | No | Yes | No | No | iOS, Android |
Manual entry, debt & savings
Manual entry, debt & savings
Manual entry, debt & savings
Manual entry, debt & savings
Manual entry, debt & savings
Manual entry, debt & savings
Table last reviewed August 2026. Verify current pricing and features with each app's website — details may change.
How we evaluated these apps
We weighted each criterion around what actually matters for budgeters in Singapore — local currency and bank support, cash and e-wallet habits, and app availability.
How quickly you can set up a budget, log spending, and understand where your money goes.
Budgeting flexibility, expense-tracking quality, debt tracking, and savings-goal features.
Bank-sync availability and reliability, the manual-entry experience, and CSV / import support.
Pricing structure, free tiers, and whether paid plans are worth it for most people.
How each app handles your financial data, and whether bank linking is required at all.
iOS / Android / web availability, currency and localization support, and who the app is built for.
App-by-app breakdown
Seedly
Best for The integrated Singapore default
Seedly is the app most Singaporeans reach for, and for good reason. It integrates with SGFinDex, so it can pull your bank balances, CPF (Ordinary and Special account), HDB loan and investment data into one view with your consent, instead of you keying it in. It is GST-aware, free, and backed by a large local community and content library. If you want the full picture of your Singapore finances in one place, Seedly is the sensible starting point — and we'd rather tell you that plainly than pretend otherwise.
Why we like it
- SGFinDex integration consolidates bank, CPF, HDB, and investment data
- Built specifically for Singapore (CPF, GST, local banks)
- Free, with a strong community and personal-finance content
- Imports transactions from major local banks
Limitations
- The integrated view means linking your financial data (via SGFinDex / bank login)
- More of a tracking-and-overview tool than a strict budgeting method
- Privacy-conscious users may prefer not to consolidate everything
Key details
DBS NAV Planner
Best for DBS and POSB customers
If you bank with DBS or POSB, NAV Planner is built into the app you already use. It automatically categorises your DBS/POSB transactions, projects cash flow, and can pull in a broader picture through SGFinDex. For DBS-centric households it is the lowest-friction option because there is nothing extra to install. It is weaker if your money is spread across several banks or if you want a dedicated budgeting method.
Why we like it
- No extra app — built into DBS/POSB digibank
- Automatic categorisation of DBS/POSB spending
- Cash-flow projection and SGFinDex consolidation
- Free
Limitations
- Best only if DBS/POSB is your main bank
- Limited manual control and budgeting methodology
- Ties your budgeting to one bank app
Key details
Planner Bee
Best for An all-in-one local money app
Planner Bee is a Singapore app that brings spending tracking together with insurance and investment management. It suits people who want a broader financial cockpit rather than a pure expense tracker, and who like the idea of seeing policies and investments alongside day-to-day spending. As a strict budgeting tool it is lighter than a dedicated budget app.
Why we like it
- Combines expense tracking with insurance and investment views
- Built for the Singapore market
- Useful for a broad financial overview
Limitations
- Budgeting depth is lighter than dedicated budget apps
- Broader scope can be more than a simple tracker needs
Key details
Hunter Vault Our app
Best for Private, gamified budgeting with nothing linked
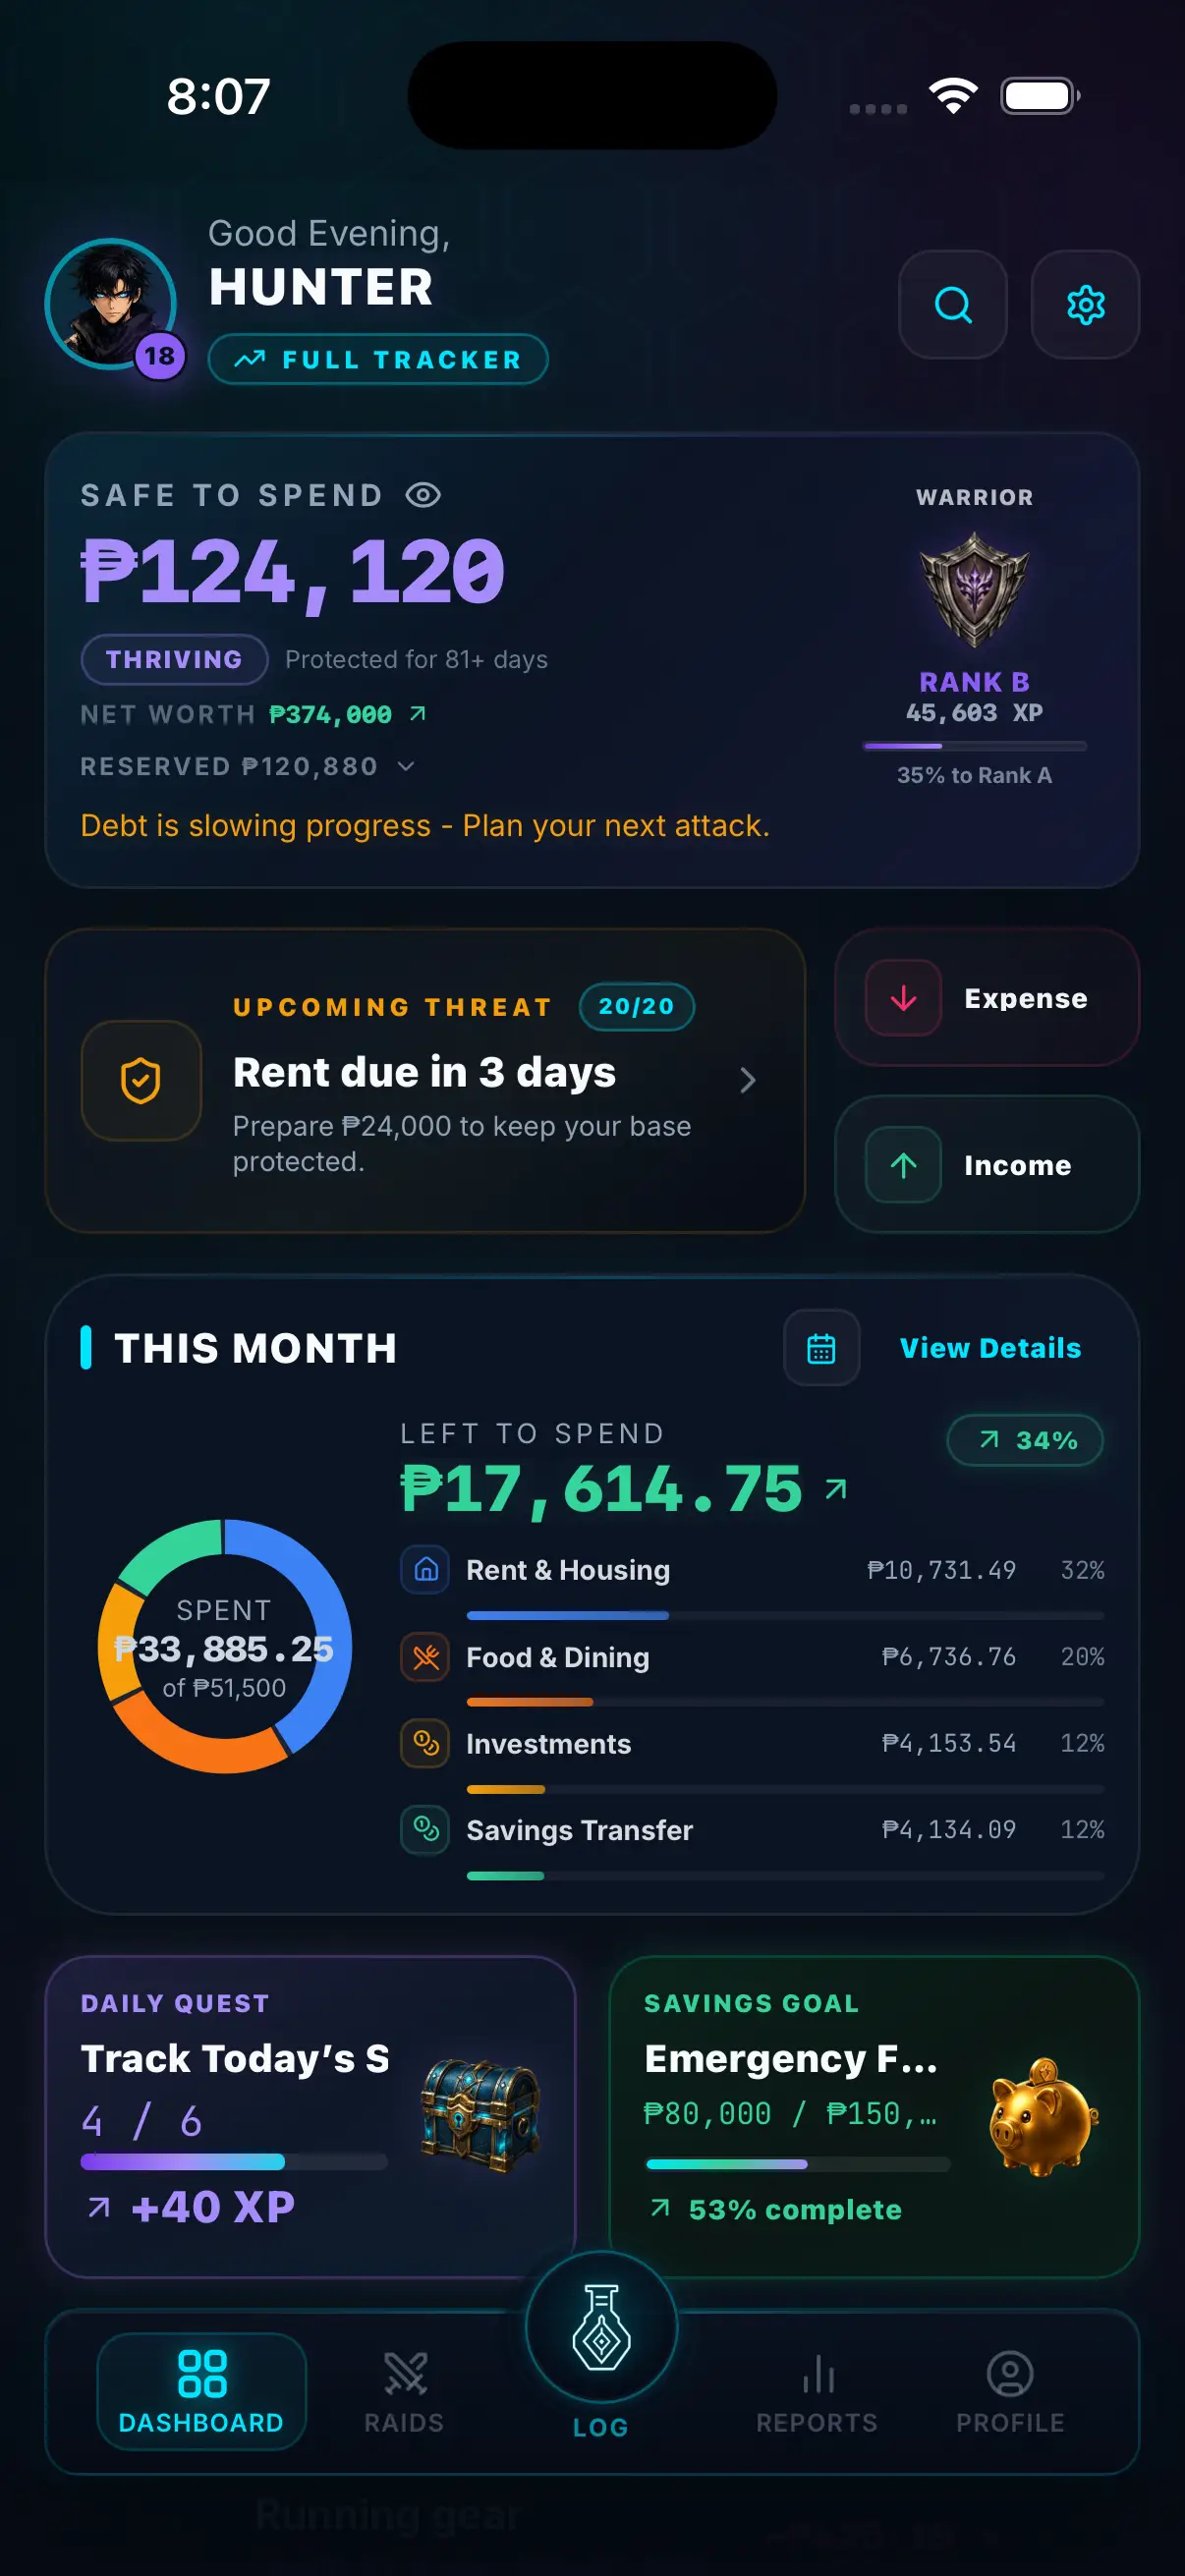
Hunter Vault is our own app, and in Singapore we're not going to pretend it beats Seedly for everyone — it doesn't. Seedly's SGFinDex and CPF integration is genuinely strong, and if you want that consolidated view, use it. Hunter Vault is for two narrower groups: people who would rather not link their bank and CPF through SGFinDex at all, and people who have downloaded Seedly (or three other apps) and stopped using them. It is fully manual and offline — nothing synced, nothing linked — and it turns logging into quests, XP, and ranks so the habit actually sticks.
Why we like it
- Nothing linked — no SGFinDex, no bank login, data stays on your device
- Gamified: XP, quests, levels, ranks, and streaks to keep you logging
- Full feature set: budgets, expenses, savings goals, debt tracking, recurring bills
- Works offline; Elite is a one-time purchase, not a subscription
- Logs PayNow, card, and cash spending in one place
Limitations
- Cannot track CPF automatically — for a CPF/net-worth view, Seedly is better
- Manual entry only; no SGFinDex or bank import
- Single-user; no household sharing
Key details
YNAB (You Need A Budget)
Best for The most structured budgeting method
YNAB brings zero-based budgeting — assign every dollar a job before you spend it. There is no local Singapore bank sync, so you log manually or import a CSV. The method is excellent and works in SGD, but the USD subscription (around S$20/month once converted) is a real cost compared with the free local apps.
Why we like it
- Rigorous zero-based method, works in SGD
- Strong debt payoff and savings tools
- Large community and learning resources
- 34-day free trial
Limitations
- No Singapore bank sync or SGFinDex integration
- USD subscription — roughly S$20/month equivalent
- Learning curve
Key details
Monefy
Best for Quick, simple manual logging
Monefy is a minimal, fast expense tracker — tap a category, enter an amount. No SGFinDex, no bank login, purely manual. It has no budgeting method, CPF view, or debt tracking, but for quickly logging a hawker meal, a Grab ride, or a PayNow transfer, it is one of the fastest tools available.
Why we like it
- Very fast manual logging
- No linking; works offline
- Visual spending wheel
Limitations
- No income budgeting, savings goals, debt tracking, or CPF
- Free version has ads
- Minimal reporting
Key details
Budgeting in Singapore
SGFinDex and Seedly — why Singapore has it easy
Singapore is unusual: SGFinDex, a government-initiated framework, lets you consolidate data from participating banks, CPF, HDB, and IRAS with your consent. Apps like Seedly use it to build a complete financial picture without constant manual input — which is why Seedly is the default recommendation for most Singaporeans. If an integrated, mostly-automatic overview is what you want, this is a genuine advantage and you should use it.
The flip side is that the integrated view depends on linking your financial data. Some people would rather not consolidate everything in one place, however secure the pipes are. For them, a manual app that links nothing is the point — not a limitation.
CPF tracking — where local apps win
CPF (your Ordinary, Special, and MediSave accounts) is central to Singapore finances, and seeing it alongside your spending is genuinely useful. Seedly and DBS NAV Planner can surface CPF balances through SGFinDex. A manual, offline app like Hunter Vault cannot pull CPF automatically — you would have to enter balances by hand, which most people won't. So if an automatic CPF and net-worth dashboard is a priority for you, a local SGFinDex-connected app is the better tool, full stop.
PayNow, cards, and cash
Everyday Singapore spending runs through PayNow, contactless cards, and GrabPay, with some cash. Bank-connected apps capture card and bank-linked activity automatically; PayNow transfers and cash still often need a glance to categorise correctly. In a manual app, you simply log each one — fast, and with no account linked. Either way, a quick logging habit is what keeps the budget accurate.
The privacy and motivation niche
Two groups are underserved by the SGFinDex-first default. The first is privacy-minded users who do not want their bank, CPF, and investments consolidated by any app. The second is people who have tried Seedly or another tracker and quietly stopped — for them the problem was never data coverage, it was staying engaged. A manual, private, gamified app speaks to both: nothing linked, and a reason to keep logging. That is the specific gap Hunter Vault fills here — not the mainstream, but a real one.
Automatic (SGFinDex) vs manual budgeting in Singapore
Unlike most of Asia, Singapore genuinely supports automatic consolidation, so the choice here is real.
**Automatic via SGFinDex (Seedly, DBS NAV Planner):** Link your data once and your bank, CPF, and investment picture updates with little effort. Best for a complete, low-maintenance overview. Requires consenting to data consolidation.
**Manual entry (Hunter Vault, Goodbudget, Monefy):** You log each expense yourself. More effort, nothing linked, maximum privacy, and the logging itself builds awareness. Cannot show CPF automatically.
**Structured manual method (YNAB):** Zero-based budgeting with manual entry — a method, not just a tracker, at a USD subscription cost.
For most Singaporeans the automatic route is the practical default, and we'll say so. The manual route is for people who deliberately don't want to link their finances, or who need the habit to feel rewarding enough to keep going.
What to look for in a budgeting app in Singapore
**Do you want the integrated SGFinDex view?** If yes, Seedly (or DBS NAV Planner for DBS/POSB users) is the natural choice. If you'd rather not link your data, look at manual apps instead.
**Is CPF visibility important?** For an automatic CPF and net-worth dashboard, use an SGFinDex-connected app. A manual app can't pull CPF for you.
**Which bank?** DBS/POSB users get NAV Planner for free inside their banking app; multi-bank users are better served by Seedly's consolidation.
**Privacy preference:** If consolidating your finances in one app bothers you, a manual, offline tool that links nothing (Hunter Vault) is built for exactly that.
**Have you quit trackers before?** If coverage was never the problem — you just stopped opening the app — a gamified tracker gives you a reason to come back that a dashboard doesn't.
**Pricing:** The strong local apps are free. YNAB is a USD subscription. Hunter Vault's Elite unlock is a one-time local purchase.
Frequently asked questions
What is the best budgeting app in Singapore?
For most Singaporeans, Seedly is the sensible default — it uses SGFinDex to pull your bank, CPF, and investment data into one view, is GST-aware, and is free. DBS/POSB users also get NAV Planner free inside their banking app. If you would rather not link your finances, or you keep abandoning trackers and want motivation, a manual gamified app like Hunter Vault fits that narrower need.
Is Seedly the best budgeting app for Singapore?
For the mainstream use case — an integrated overview of your bank balances, CPF, and investments with minimal manual input — Seedly is hard to beat, thanks to its SGFinDex integration and local focus. It is less of a strict budgeting method and more of a consolidated tracker, and it does rely on linking your data. If either of those is a mismatch for you, a method-driven app (YNAB) or a private manual app (Hunter Vault) may suit you better.
Which budgeting app tracks CPF?
Apps that connect through SGFinDex can display your CPF balances — Seedly and DBS NAV Planner are the common choices. Manual, offline apps like Hunter Vault cannot pull CPF automatically; you would have to enter balances by hand. If an automatic CPF and net-worth view matters to you, choose an SGFinDex-connected app.
Can I budget in Singapore without SGFinDex or bank linking?
Yes. Manual apps link nothing. Hunter Vault, Goodbudget, and Monefy let you log PayNow, card, and cash spending by hand, with no SGFinDex connection and no bank login. You trade automatic consolidation for privacy and the spending awareness that manual logging builds — you just won't get an automatic CPF view.
Are there free budgeting apps in Singapore?
Yes. Seedly is free, DBS NAV Planner is free inside the DBS/POSB app, and Planner Bee is free to use. Hunter Vault is free to start with all core features. Monefy has a free version with ads. YNAB requires a USD subscription after its trial.
Is Hunter Vault available in Singapore?
Yes. Hunter Vault is on the App Store and Google Play and works in SGD. It is manual and offline by design — nothing linked through SGFinDex or a bank — and the Elite unlock is a one-time purchase. It is best for privacy-first users or people who want gamified motivation, rather than those who want an automatic CPF dashboard.
More Hunter Vault guides
Level up your money
Track spending, complete quests, and build better financial habits — the RPG way. Free to start, no bank linking required.
Free to start · No account needed · Works offline