Best Mint Alternatives in 2026 (Tested Replacements)
Mint shut down on March 23, 2024 when Intuit migrated its users to Credit Karma. Mint did passive bank-sync tracking — most users want a replacement that does automatic categorization and a spending overview. Others used Mint's shutdown as a reason to try a different approach entirely. This guide covers both: apps that most closely replicate what Mint did, and apps that offer a meaningfully different path.
On this page
Our picks for different budgeters
Side-by-side comparison
| App | Best for | Price | Bank sync | Manual entry | Debt tracking | Savings goals | Platforms |
|---|---|---|---|---|---|---|---|
| Monarch Money | Best overall Mint replacement: bank sync, dashboard, net worth | $14.99/mo or $99.99/yr (Core) | Yes | Yes | Yes | Yes | iOS, Android, Web |
| Empower | Free bank sync + investment view | Free | Yes | Limited | Yes | Limited | iOS, Android, Web |
| YNAB | Zero-based, most behavior change | $14.99/mo or $109/yr | Yes | Yes | Yes | Yes | iOS, Android, Web |
| Rocket Money | Subscription detection, bill cancellation | Free / Premium $7–$14/mo | Yes | No | No | Limited | iOS, Android |
| Simplifi by Quicken | Clean spending plan, bank sync | $6.99/mo or $47.88/yr | Yes | Yes | Yes | Yes | iOS, Android, Web |
| Hunter Vault Our app | Manual, gamified, no bank required | Free (one-time Elite upgrade; optional subscriptions) | No | Yes | Yes | Yes | iOS, Android |
Manual entry, debt & savings
Manual entry, debt & savings
Manual entry, debt & savings
Manual entry, debt & savings
Manual entry, debt & savings
Manual entry, debt & savings
Table last reviewed October 2026. Verify current pricing and features with each app's website — details may change.
How we evaluated these apps
We score every app against the same criteria, so the recommendations stay consistent and comparable.
How quickly you can set up a budget, log spending, and understand where your money goes.
Budgeting flexibility, expense-tracking quality, debt tracking, and savings-goal features.
Bank-sync availability and reliability, the manual-entry experience, and CSV / import support.
Pricing structure, free tiers, and whether paid plans are worth it for most people.
How each app handles your financial data, and whether bank linking is required at all.
iOS / Android / web availability, currency and localization support, and who the app is built for.
App-by-app breakdown
Monarch Money
Best for Former Mint users who want automatic sync and a clean dashboard
Monarch Money is the most popular post-Mint destination, and for good reason: it covers the same ground Mint did — bank sync, spending categories, net worth tracking, and a dashboard overview — while adding features Mint lacked, including household sharing and better goal tracking. The methodology is softer than YNAB — you set monthly category budgets rather than assigning every dollar before you spend it — which is closer to how Mint worked. Core is $99.99/year with a 7-day trial. There is no permanently free tier, but for most former Mint users, this is the most direct functional replacement.
Why we like it
- Bank sync and dashboard match the passive Mint workflow
- Net worth tracking, goals, and household sharing built in
- Cleaner interface than Mint with more features
- Multi-user support — good for couples
- Plus tier adds forecasting and business tracking
Limitations
- $99.99/year Core — no free tier beyond 7-day trial
- Softer methodology than YNAB — tracks spending, does not guide it
- Primarily US-focused for bank sync
- No zero-based allocation for strict budgeters
- Plus tier ($199.99/yr) required for forecasting features
Key details
Empower
Best for Free bank-sync replacement with investment and net worth tracking
Empower (formerly Personal Capital) is completely free and offers bank sync across checking, savings, credit, and investment accounts. It shows spending by category, tracks net worth, and provides an investment portfolio overview — all at no cost. The approach is passive, like Mint was: it records what happened rather than helping you plan ahead. If Mint's free, automatic tracking was what you valued and you never found it produced much behavior change anyway, Empower covers the same ground without a subscription.
Why we like it
- Completely free — no subscription at any tier
- Bank and investment account sync
- Net worth tracking is strong and well-visualized
- No methodology commitment required
- Retirement planning tools included
Limitations
- Passive tracking — no planning before you spend
- Manual entry is limited
- Wealth management advisory may prompt outreach from advisors
- US-focused
- Will not change spending patterns any more than Mint did
Key details
YNAB
Best for People who want more behavior change than Mint ever produced
YNAB (You Need A Budget) is the opposite of Mint in one important way: Mint showed you where money went; YNAB forces you to decide where money goes before you spend it. The zero-based methodology assigns every dollar to a category at the start of each month. This active engagement is why YNAB users commonly report saving more than they expected in the first year. The trade-off is a steep learning curve, consistent effort every month, and a $109/year subscription. There is a 34-day free trial, and students may qualify for a free year.
Why we like it
- Zero-based methodology produces real, measurable behavior change
- Active planning framework — you decide before spending, not after
- Bank sync and manual entry both supported
- Debt payoff and savings goal tracking built in
- 34-day free trial; student plan available
Limitations
- $14.99/month or $109/year — no permanent free tier
- Steep learning curve; takes weeks to set up correctly
- Active engagement required every month — not passive
- More methodology commitment than most Mint users expect
- Primarily US and Canada for bank sync reliability
Key details
Rocket Money
Best for People who primarily want subscription and bill detection
Rocket Money is not a full Mint replacement — it is a spending awareness and bill management tool. It connects to your bank, detects subscriptions, and will negotiate or cancel bills on your behalf (Premium only). If you used Mint mainly to check your balances and notice forgotten subscriptions, Rocket Money handles that use case. For full budgeting — category tracking, debt, goals — it falls short of what Mint offered. The free tier detects subscriptions; Premium is $7–$14/month (you choose the amount in that range).
Why we like it
- Subscription detection is genuinely useful and accurate
- Bill negotiation and cancellation on your behalf (Premium)
- Free tier covers the core subscription awareness features
- Easy setup — no methodology required
- Spending overview and balance tracking included
Limitations
- Not a full budgeting replacement for Mint — no detailed category budgets
- No debt tracking
- No savings goals
- No manual entry for cash or offline transactions
- iOS and Android only — no web app
Key details
Simplifi by Quicken
Best for People who want a lighter, cleaner alternative to Monarch Money at a lower price
Simplifi is a streamlined bank-sync budgeting app from Quicken. It tracks spending by category, supports recurring transactions, and shows where you stand against monthly limits via spending watchlists. The interface is clean and setup is relatively fast. At $47.88/year ($3.99/month billed annually), it costs less than Monarch Money and covers similar territory for users who do not need net worth forecasting or household sharing. US-focused bank sync.
Why we like it
- Clean interface with faster setup than heavier alternatives
- Spending watchlists and category limits
- Recurring transaction tracking is strong
- Bank sync reliability is well-reviewed
- Lower cost than Monarch Money at annual price
Limitations
- No free tier — trial only
- Primarily US-focused for bank sync
- Not a zero-based tool — spending plan without strict allocation
- Less community and learning resources than YNAB
- No investment or net worth tracking depth of Empower
Key details
Hunter Vault Our app
Best for Mint users who had automatic sync for years and still overspent, and are willing to try manual tracking
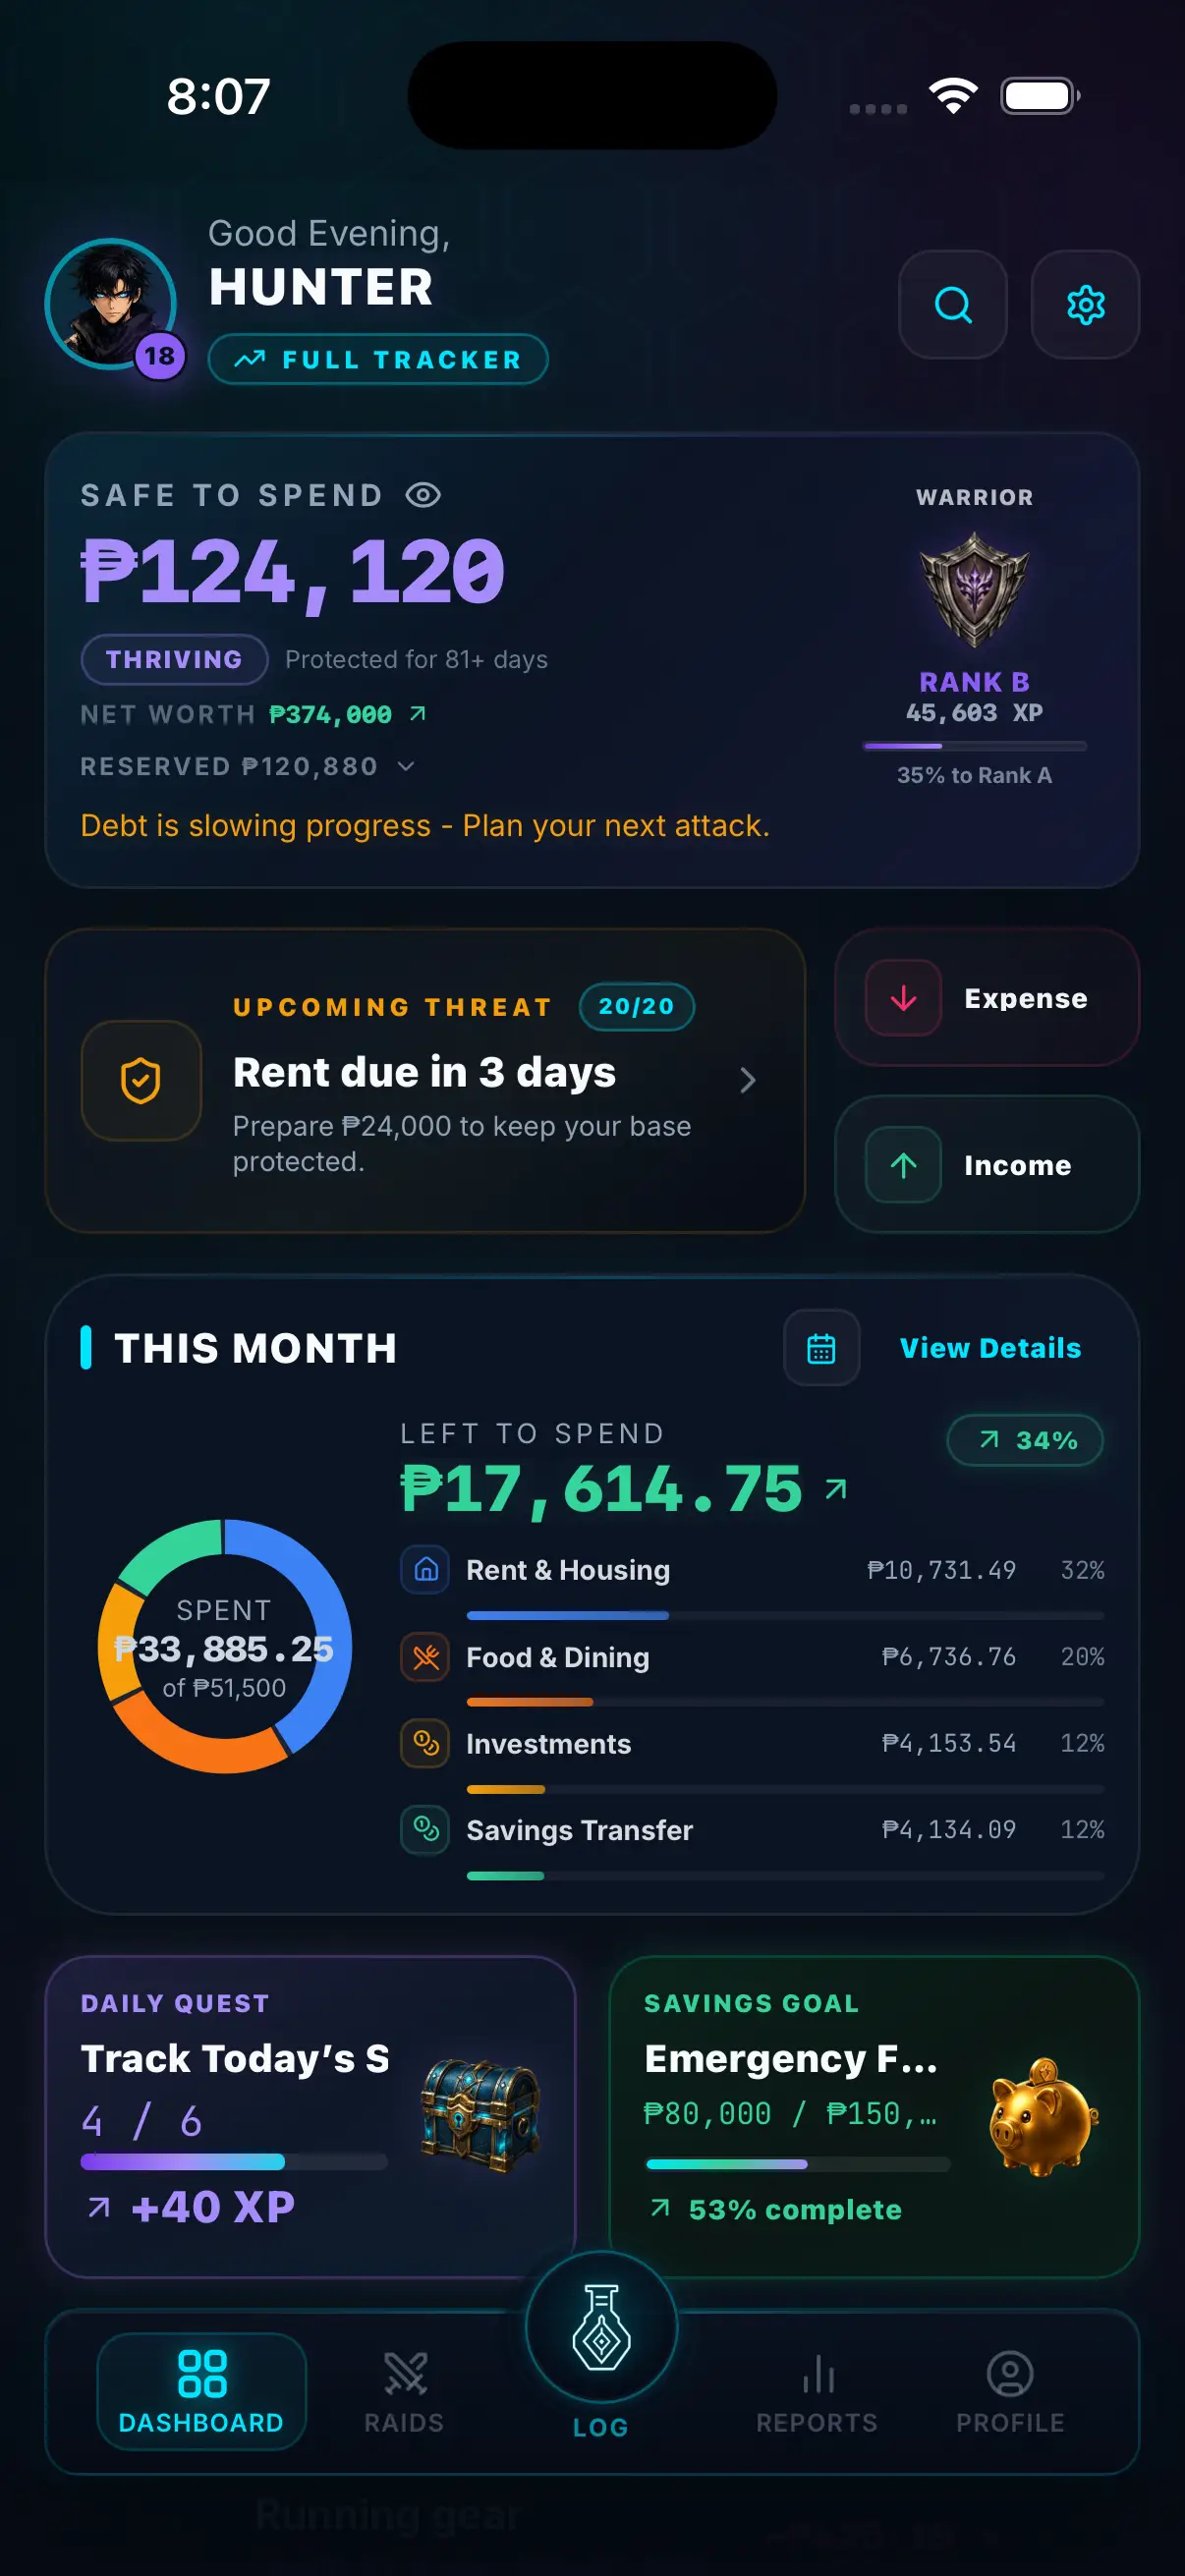
Hunter Vault takes the opposite approach from Mint: no bank connection, no automatic import, and a gamified RPG progression layer that makes manual logging a habit rather than a chore. Quests, XP, levels, ranks, and achievements reward the manual engagement that passive apps like Mint never required. The financial tools are complete: budget categories, expense tracking, debt tracking, and savings goals. Free core is usable with limits (8 budgets, 3 recurring, 5 accounts, 3 debts, 2 goals). Elite is a one-time $15.99 purchase that removes limits. Budgeting never requires a subscription — Hunter Pass and cloud sync are optional.
Why we like it
- Budgeting never requires a subscription — Elite is one-time; Hunter Pass and cloud sync are optional
- Gamified habit layer makes manual logging engaging rather than tedious
- No bank connection — no data exposure risk from third-party bank aggregators
- Budget tracking, debt tracking, and savings goals included
- Free core works indefinitely with limits (Elite removes them for one-time cost)
Limitations
- No bank sync — you enter transactions manually or import a CSV from your bank
- Mobile-first — no web entry interface
- Manual entry is more effort than Mint's automatic import
- Gamification layer is not for every user
- Smaller community than established alternatives
Key details
Context and considerations
Why people look for different approaches after Mint shut down
Mint's shutdown on March 23, 2024 created a choice for its former users that the app itself never forced: whether to keep doing passive automatic tracking or try something different. Most users fell into recognizable groups:
Passive trackers who want a replacement: These users relied on Mint's automatic categorization and dashboard. They want a like-for-like swap with minimum friction. Empower (free) or Monarch Money ($99.99/yr) are the best fits — both replicate the passive, bank-synced Mint model.
Active budgeters who used Mint for data: Some users connected Mint to everything but still maintained their own spreadsheets or made deliberate budget decisions. For these users, Mint was a data source more than a budgeting tool. YNAB or Simplifi may produce better outcomes by adding structure.
Subscription hunters: Some Mint users primarily wanted to catch forgotten charges and track recurring bills. Rocket Money handles this use case with a free tier and bill negotiation in Premium.
People ready to try something new: A small but vocal group realized the Mint shutdown was a moment to assess whether years of passive synced data had actually changed their spending. For this group, the answer was often "no" — and the shutdown became motivation to try an actively engaging method. Hunter Vault and YNAB are the two most different approaches from Mint.
There is no wrong answer. The right replacement is the one that matches how you actually behave with money, not how you intend to.
Do you need bank sync in a Mint replacement?
Mint was built entirely around bank sync. Its entire value proposition was automatic: connect your accounts, Mint categorizes your transactions, and you see a dashboard. No entry required.
The question after Mint is whether you want to keep that automatic model — or whether you are willing to try something different.
If you want to keep bank sync: Monarch Money is the most direct replacement. Empower is free. Simplifi is cheaper than Monarch. All three connect to your bank and categorize automatically.
If you want to try manual tracking: Goodbudget (envelope method) and Hunter Vault (gamified) both require you to enter transactions yourself. Many former Mint users found that a year or more of automatic data changed nothing — the shutdown was a chance to try the opposite.
The case for manual tracking is simple: you notice spending more when you log it yourself. The friction is the feature. Passive bank sync is convenient, but convenience and awareness are not the same thing.
If you do go manual, the biggest success factor is a habit layer — something that makes you return to the app regularly. YNAB provides this through methodology. Hunter Vault provides this through game mechanics.
How to choose the right Mint alternative
Start with the use case that matches how you actually used Mint:
"I want exactly what Mint did": Monarch Money is the most popular direct replacement. Bank sync, dashboard, net worth, categories — all there.
"I want free and I want bank sync": Empower. Completely free, bank sync, net worth and investment tracking. Passive, like Mint was.
"I want real behavior change": YNAB. Zero-based budgeting means every dollar gets assigned before you spend it. Steep learning curve, but produces measurable results Mint never delivered.
"I mainly want to stop paying for forgotten subscriptions": Rocket Money. Free tier detects subscriptions. Premium negotiates and cancels bills.
"I want a cheaper bank-sync option than Monarch": Simplifi by Quicken at $47.88/year.
"I want to budget without linking my bank": Goodbudget uses the envelope method. Hunter Vault uses gamification. Both are manual — no bank connection.
"Mint's data never changed my spending anyway": Hunter Vault — the manual engagement forces awareness the passive feed never did. Quests, XP, and levels make the logging habit stick rather than requiring willpower alone.
One honest caution: passive tracking apps — including Monarch and Empower — tend to produce the same behavioral results Mint produced. The data is useful. But seeing where money went after the fact does not reliably change where money goes next month. If that pattern sounds familiar, the bank-sync apps will likely continue it. The apps that break that pattern (YNAB, Hunter Vault) require more engagement but produce more change.
Frequently asked questions
What is the best Mint replacement?
Depends on use case. Monarch Money is the most popular direct replacement — it covers bank sync, net worth, and a spending dashboard like Mint did, with more features added. Empower if you want free. YNAB if you want your spending to actually change (zero-based methodology produces more behavior change than Mint's passive model). Hunter Vault if you want gamified manual tracking with no subscription required.
Is there a free Mint alternative?
Empower (formerly Personal Capital) is free and includes bank sync, spending categories, and net worth tracking. Hunter Vault's core budgeting is also free with limits (8 budgets, 3 recurring, 5 accounts, 3 debts, 2 goals) — budgeting never requires a subscription. Elite is a one-time $15.99 to remove limits.
Did Mint sell its data when it shut down?
Mint migrated users to Credit Karma — both are owned by Intuit. Your data was not sold to third parties but moved within the Intuit ecosystem. If data privacy is a concern, manual apps like Hunter Vault or Goodbudget never connect to your bank, so there is no third-party bank aggregator involved.
Will Monarch Money replace everything Mint had?
For most Mint users, yes — and it adds features Mint lacked, including net worth tracking, better goal management, and household sharing. The methodology is passive like Mint: it tracks spending after the fact rather than guiding decisions before spending. YNAB provides more behavioral structure if you want a more directive approach.
Is Hunter Vault a good Mint alternative?
For a specific type of former Mint user, yes: someone who had a fully synced app for years and still overspent, and is ready to try the opposite approach. Manual logging plus game mechanics forces awareness the passive feed did not. But if you want automated bank sync, Monarch Money or Empower are better fits — Hunter Vault has no bank connection by design.
More Hunter Vault guides
Level up your money
Track spending, complete quests, and build better financial habits — the RPG way. Free to start, no bank linking required.
Free to start · No account needed · Works offline