- Apple lists the iPhone Duo in the Philippines at ₱159,990 (256GB) to ₱254,990 (2TB), available from October 30, 2026.
- On a true 0% plan, the 256GB model is ₱13,332.50 a month over 12 months, ₱6,666.25 over 24 and ₱4,444.17 over 36.
- Not every "0%" totals the cash price. Home Credit's reported ₱6,809 a month for 24 months adds up to ₱163,416, which is ₱3,426 more than Apple's price.
- On a regular card installment at a 1% monthly add-on, 24 months would cost ₱198,387.60, or ₱38,397.60 more than cash.
- If your phone still works, save the monthly amount first. Three months of saving it proves the plan fits, and you can still buy on 0% later.
The iPhone Duo is Apple’s first foldable iPhone, and in the Philippines it starts at ₱159,990. Almost nobody pays that in one go. The real question is what the monthly will be, which plan is actually 0%, and whether the payments fit your budget for two or three years.
This guide answers those three questions. It lists the iPhone Duo’s Philippine prices, works out the monthly cost for every term, and shows what each payment route adds up to. Every price and promo here comes from the store’s, bank’s or carrier’s own announcement, checked on October 25, 2026.
Hunter Vault is an independent, RPG-inspired budgeting app. It isn’t affiliated with, endorsed by, or connected to Apple, Power Mac Center, Beyond the Box, Digital Walker, Digimap, The Loop, Home Credit, Smart, BPI or EastWest. Their names are used only to describe the offers this guide explains. Promos change quickly during a launch, so confirm the terms with the store and your bank before you pay.
Quick Answer: How Much Is the iPhone Duo per Month?
On a true 0% installment, the 256GB iPhone Duo costs ₱13,332.50 a month for 12 months, ₱6,666.25 a month for 24 months or ₱4,444.17 a month for 36 months. That’s Apple’s ₱159,990 price divided by the months. A plan only costs that little if it has no fee, no price markup and no missed month. Ask for the total amount payable and check that it matches the cash price.
iPhone Duo Price in the Philippines
Apple’s Philippine store page lists four storage sizes in two colors, Night Sky and Star White. It says the phone is “available starting October 30”. Pre-orders opened on October 16.
| Storage | Apple Philippines price |
|---|---|
| 256GB | ₱159,990 |
| 512GB | ₱175,990 |
| 1TB | ₱207,990 |
| 2TB | ₱254,990 |
Source: Apple’s Philippine online store, checked October 25, 2026. Apple lists prices with taxes included.
Some launch roundups list a higher “regular SRP” for the iPhone Duo. One shows ₱170,990 for 256GB, with ₱159,990 as a reseller promo. Apple’s own store lists ₱159,990. If a store’s discount is measured from a higher starting price, the saving may be smaller than it looks, so compare against Apple’s price.
Monthly Cost at 0%, for Every Storage Size
At 0%, the monthly amount is simply the price divided by the number of months. These are our own calculations from Apple’s prices.
| Storage | 12 months | 24 months | 36 months |
|---|---|---|---|
| 256GB (₱159,990) | ₱13,332.50 | ₱6,666.25 | ₱4,444.17 |
| 512GB (₱175,990) | ₱14,665.83 | ₱7,332.92 | ₱4,888.61 |
| 1TB (₱207,990) | ₱17,332.50 | ₱8,666.25 | ₱5,777.50 |
| 2TB (₱254,990) | ₱21,249.17 | ₱10,624.58 | ₱7,083.06 |
Not every store offers every term on every card. Use the table to see what a term would cost, then check that your store and card actually offer it.
To try a different price, a fee or a regular add-on rate, use the credit card installment calculator. It shows the monthly payment, the total, and the effective interest rate.
Where You Can Get the iPhone Duo on Installment
There are four routes, and they don’t all work the same way. Here’s what each one offers as of October 25, 2026.
1. Credit card installment at an Apple reseller
This is the most common route. You buy at a reseller and your bank splits the price into monthly payments on your card.
- Power Mac Center offers cash, straight payment and “flexible installment plans of up to 24 months through major credit cards and Home Credit”, according to its pre-order announcement as reported by Gizguide on October 16. The same announcement lists extended installment offers for BPI cardholders until November 30, 2026 and Security Bank cardholders until November 1, 2026.
- BPI’s FlexipayZero page for Power Mac Center offers “up to 36 months 0% interest” on Apple products, with a ₱3,000 minimum single-receipt purchase. It says the terms “may be available for select items only”, so ask whether the iPhone Duo qualifies for 36 months.
- EastWest’s iPhone Duo promo at Power Mac Center and The Loop offers 0% for 12 or 24 months on pre-orders, from October 16 to 31, 2026. Billing starts on the third statement after you buy. The page says the 0% pricing “is based on Power Mac Center and The Loop’s non-installment pricing”, so the installment total should match the cash price. Ending the plan early costs 5% of the remaining principal or ₱500, whichever is higher.
- Beyond the Box, Digital Walker, Digimap and The Loop also sell the iPhone Duo with bank installment offers, according to GadgetMatch’s buyer’s guide. GadgetMatch notes that many of the monthly figures in launch roundups are its own calculations, not confirmed store quotes.
2. Home Credit
Home Credit is a consumer finance company, not a bank card. It offers the iPhone Duo with “official 0% interest and zero-down-payment installment plans” over 24 months, as reported by Gizguide on October 22. Here’s the reported monthly for each size, multiplied out:
| Storage (Apple price) | Monthly × 24 | Total paid | Above Apple’s price |
|---|---|---|---|
| 256GB (₱159,990) | ₱6,809 | ₱163,416 | ₱3,426 |
| 512GB (₱175,990) | ₱7,479 | ₱179,496 | ₱3,506 |
| 1TB (₱207,990) | ₱8,809 | ₱211,416 | ₱3,426 |
| 2TB (₱254,990) | ₱10,769 | ₱258,456 | ₱3,466 |
The totals and differences are our own calculations. The report doesn’t explain the gap of about ₱3,400 to ₱3,500. It may be a fee that isn’t in the article. Whatever it is, it’s real money: on the 256GB model it works out to an effective rate of about 0.17% a month, or about 2% a year. That’s far cheaper than a regular card installment, but it isn’t the same as paying cash. Ask Home Credit for the total amount payable and any fees before you sign.
3. Smart postpaid plans
Smart offers the iPhone Duo on Postpaid Plans+ 1999, from ₱6,304 a month with a 24-month lock-in, according to Gadget Pilipinas on October 16. The plan includes 12 months of UNLI 5G and an Unli App bundle. The report describes the monthly as a zero-interest installment over up to 24 months with select banks. Renewing postpaid subscribers can spread the phone over up to 36 months on their bill.
The report doesn’t split the ₱6,304 into the plan fee and the phone. Before you compare it with a card installment, ask Smart for two numbers: the total you’ll pay over the 24 months, and the part of it that’s the phone. A postpaid plan is only cheaper if you’d otherwise pay a similar amount for mobile data. For example, if you’d normally spend ₱300 a month on load, most of the plan fee is a new cost.
Globe also lists the iPhone Duo under its Platinum plans. We couldn’t get a current, dated iPhone Duo price from Globe’s own pages, so check the cash-out and lock-in on globe.com.ph directly.
4. Apple’s own store
Apple’s Philippine iPhone Duo page lists cash prices and free delivery, but no installment or monthly payment option, as of October 25. In the US, Apple advertises iPhone Duo leases from $57.99 a month in its October 15 announcement, but that offer isn’t on the Philippine page.
What Each Way of Paying Really Costs
Here’s the total paid for the 256GB iPhone Duo by each route. The add-on rows use a regular 1% monthly add-on, the most a bank may charge on card installments under the BSP’s cap. Items that aren’t on a 0% promo usually go on a regular plan like this. BDO, for example, lists its regular in-store installment at a 1% monthly add-on.
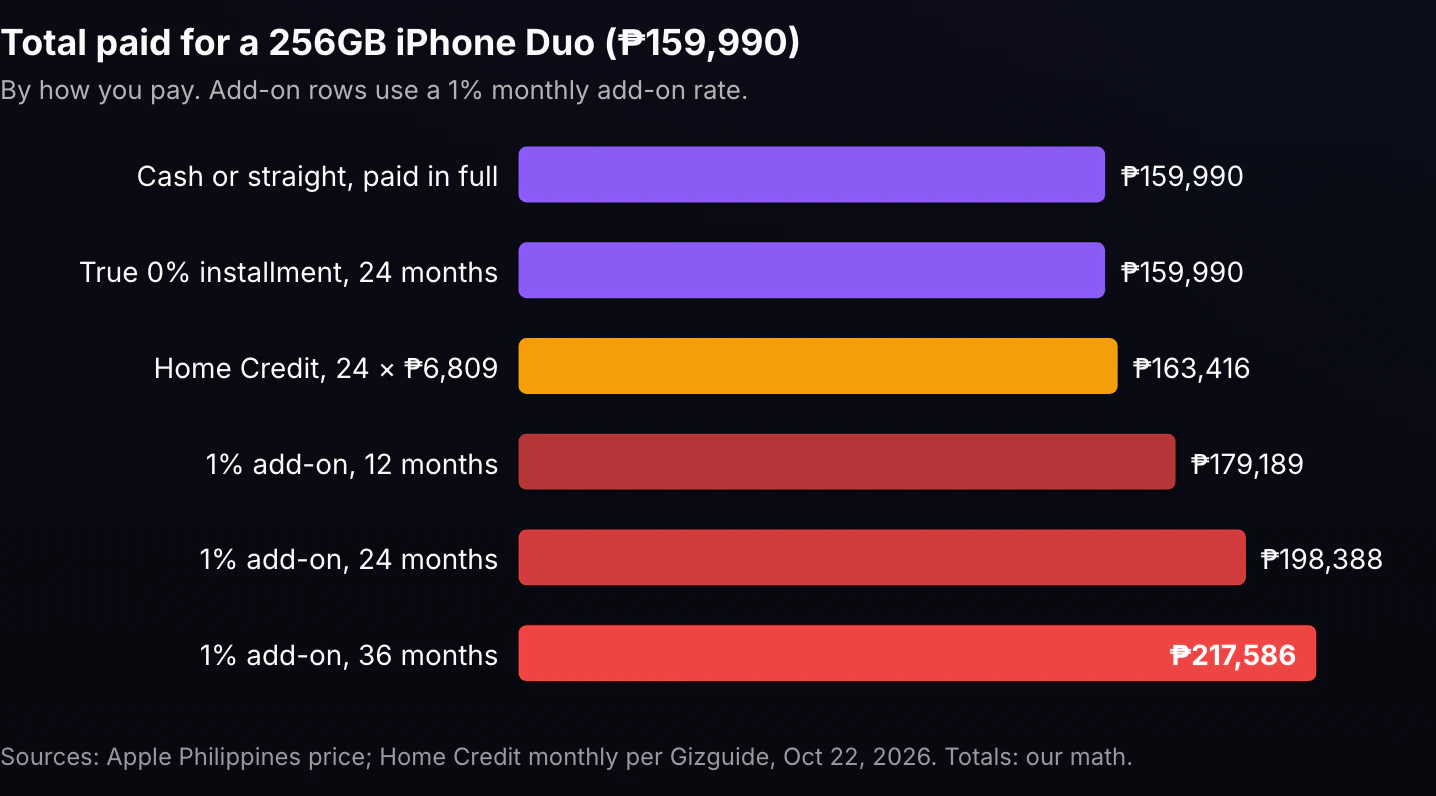
A regular add-on plan is priced on the full ₱159,990 every month, even as your balance shrinks. Over 24 months that’s ₱1,599.90 a month in add-on, for an effective rate of about 1.8% a month. Our credit card installment guide explains how add-on rates work and what the BSP allows.
The Catches on a “0%” iPhone Duo Plan
A 0% plan for a ₱159,990 phone has the same catches as any card installment. The size of the purchase just makes them bigger.
- The full price usually comes off your credit limit. With most bank installments, the whole amount is held against your available credit, not one month’s payment. A ₱159,990 phone needs ₱159,990 of free limit, which is more than many cards have. BPI’s Power Mac Center page mentions a “Bonus Madness Limit”, an installment-only limit of up to 100% of your regular credit line for qualified cardholders. Ask your bank how your card handles it.
- A missed month ends the 0%. EastWest’s terms say the 0% applies only if you pay your total statement balance in full. Paying only the minimum adds interest. BPI and Metrobank, for example, list a 3% monthly finance charge on unpaid balances for most of their cards, plus a late fee.
- Ending early costs a fee. If you want out later, for example to sell the phone, expect a pre-termination fee. EastWest’s is 5% of the remaining principal or ₱500, whichever is higher.
- Long terms outlast the excitement. A 36-month plan that starts in November 2026 has its last payment around October 2029. Check whether you’ll still be glad to pay ₱4,444 a month in year three.
- Several plans add up. If you already pay other installments, add this monthly to that total before you decide. Our installment guide shows how to list them in one place.
Save First or Pay Monthly? Run a Payment Rehearsal
Saving for the phone and paying it off monthly can cost the same each month. The difference is what happens when a month goes wrong. With savings, nothing happens. With an installment, a late fee and interest can land on your card.
If your current phone works, there’s a simple test that keeps both doors open.
Pick the monthly you'd pay
Choose the term you’d take and find the monthly in the table above. For the 256GB model on 24 months, that’s ₱6,666.25.
Save that amount for three months
Every payday, move the monthly amount into a separate savings account or e-wallet you don’t spend from. Do it before anything else. If a month is hard to cover, the plan wasn’t going to fit either.
Decide with the rehearsal money in hand
After three months you have about ₱20,000 saved. If paying it felt fine, you can buy on a true 0% plan and keep the savings as a buffer for the first payments. Or you can keep saving and buy in cash. If paying it felt tight, you’ve found that out without a two-year contract.
Here’s what saving the full amount looks like for the 256GB model (our own calculations):
| Goal | Save per month | Save per week |
|---|---|---|
| Cash in 6 months | ₱26,665 | about ₱6,153 |
| Cash in 9 months | ₱17,777 | about ₱4,102 |
| Cash in 12 months | ₱13,333 | about ₱3,077 |
A 12-month savings plan takes the same monthly amount as a 12-month 0% installment, but nothing is held against your credit limit and you can pause any time. If you have a 13th month pay coming in December, it can cover a big part of the goal. Our guide on how to budget your 13th month pay shows how to split it so bills and savings come first.
To set a target date and see the monthly amount, use the sinking fund calculator. For a peso-a-day style plan, the printable ipon challenge tracker works too. A sinking fund is exactly this kind of saving: money set aside on a schedule for a known purchase.
Lower the Amount You Finance
Whatever route you choose, a smaller amount to finance means a smaller monthly and less risk.
- Trade in or sell your old phone. Power Mac Center (UpTrade), Beyond the Box (BoxTrade) and Digimap (DigiTrade) run trade-in programs, per GadgetMatch. The value depends on the model, storage and condition. Selling it yourself may get more, but takes longer.
- Pick the storage you’ll actually use. Going from 512GB down to 256GB saves ₱16,000, or ₱666.67 a month on a 24-month plan.
- Count the freebies at what they’re worth to you. Launch bundles, accessory vouchers and raffles don’t lower the price of the phone. Don’t let a bundle push you to a bigger model or a longer term.
- Put any bank discount toward the price, not upgrades. Some cards cut a few thousand pesos off during the launch. If you get one, keep the storage you planned and take the lower total.
A Quick Checklist Before You Sign
Before you commit to an iPhone Duo installment, get these answers in writing or on screen:
- The cash price at that store, and how it compares with Apple’s ₱159,990.
- The total amount payable on the plan, including fees. If it’s above the cash price, the plan isn’t really 0%.
- The monthly amount and number of months, and when the first payment is billed.
- How much of your credit limit the plan will hold.
- The pre-termination fee, in case you want to end the plan early.
- For a postpaid plan, the plan fee and phone portion of the monthly, and the lock-in.
If you’d still want the phone at the cash price, and the monthly would fit even in a bad month, a true 0% plan is a reasonable tool. If the low monthly is what makes it feel affordable, wait and save.
Where Hunter Vault Fits
Hunter Vault is our own app, so take this as a recommendation from the people who build it. It’s a manual budgeting app with an RPG layer of quests, XP, ranks and streaks. It never connects to your bank, and it supports the Philippine peso (₱). Two of its regular features fit a big phone purchase:
- Saving first: a savings goal. Create a savings goal called “iPhone Duo” with the price as the target, your buy date as the deadline and a monthly contribution. Log each deposit with Add funds and the progress bar fills. A goal funding-day reminder is optional. The free plan includes 2 savings goals.
- Paying monthly: a debt. Add the plan as a debt (a Dungeon Raid) of the CC installment plan type. It shows “Installment #x of y”, so the months left are always in view, and Pay Debt logs each payment. Hunter Vault never adds interest on its own, so enter the total you’ll actually pay. An optional phone reminder fires 3 days before the due day. The free plan tracks up to 3 debts. See the debt tracker.
Awakened Hunter, a one-time purchase, removes the free plan’s limits. Budgeting never requires a subscription. The app is on iOS and Android.
Final Takeaway
The iPhone Duo starts at ₱159,990 in the Philippines. On a true 0% plan, that’s ₱6,666.25 a month for 24 months or ₱4,444.17 for 36. But “0%” only means 0% if the total amount payable matches the cash price. Home Credit’s reported plan totals about ₱3,400 more, and a regular 1% add-on plan over 24 months costs ₱38,397.60 more.
If your phone still works, rehearse the monthly payment for three months before you sign anything. You’ll either have a buffer for a 0% plan or a head start on paying cash. Start by setting up a sinking fund with your target date.
This is general educational content, not financial advice. Prices, promos and installment terms vary by store, card and carrier, and change often during a launch. Confirm the total amount payable before you buy, and set big purchases after your essentials, bills and savings.
Frequently Asked Questions
How much is the iPhone Duo in the Philippines?
Apple's Philippine online store lists the iPhone Duo at ₱159,990 for 256GB, ₱175,990 for 512GB, ₱207,990 for 1TB and ₱254,990 for 2TB, as of October 25, 2026. Apple says it's available starting October 30, 2026. Some retailer listings quote a higher regular price, so compare any "discount" with Apple's own price.
How much is the iPhone Duo monthly on installment?
On a true 0% plan, divide the price by the months. The 256GB model is ₱13,332.50 a month for 12 months, ₱6,666.25 for 24 months and ₱4,444.17 for 36 months. The 512GB model is ₱14,665.83, ₱7,332.92 and ₱4,888.61. Plans with an add-on rate or a fee cost more, so ask for the total amount payable, not just the monthly.
Can I get the iPhone Duo on 0% installment for 36 months?
Only with some cards and stores. As of October 2026, Power Mac Center advertises 0% plans of up to 24 months through major credit cards and Home Credit. BPI's FlexipayZero page for Power Mac Center offers up to 36 months at 0% on select items, and EastWest's iPhone Duo promo is 12 or 24 months. Confirm the term with the store and your bank before you pay.
Does Home Credit offer the iPhone Duo on installment?
Yes. As reported on October 22, 2026, Home Credit offers the iPhone Duo at 0% interest with zero down payment over 24 months, from ₱6,809 a month for 256GB. Multiplied out, that's ₱163,416, or ₱3,426 more than Apple's ₱159,990 price. The report doesn't explain the gap, so ask Home Credit for the total amount payable and any fees before you sign.
Can I buy the iPhone Duo on installment from Apple's Philippine online store?
Apple's Philippine iPhone Duo page doesn't list an installment or monthly payment option, as of October 25, 2026. Card installment plans for the iPhone Duo in the Philippines run through Apple resellers such as Power Mac Center, Beyond the Box, Digital Walker, Digimap and The Loop, through Home Credit, and through Smart postpaid plans.
Is the Smart postpaid iPhone Duo plan cheaper than buying it outright?
It depends on what you already pay for mobile data. Smart advertises the iPhone Duo on Postpaid Plans+ 1999 from ₱6,304 a month with a 24-month lock-in. Reports don't split that monthly into the plan fee and the phone, so ask Smart for the total payable over 24 months. Then compare it with the phone's cash price plus 24 months of the plan or load you'd pay anyway.
Is it better to save for the iPhone Duo or buy it on installment?
If your current phone works, saving first usually wins. Saving ₱13,332.50 a month for 12 months is the same monthly amount as a 12-month 0% plan, but nothing is held against your credit limit, there's no late fee if a month goes wrong, and you can stop if you change your mind. A true 0% plan makes sense only if the monthly fits your budget for the whole term.